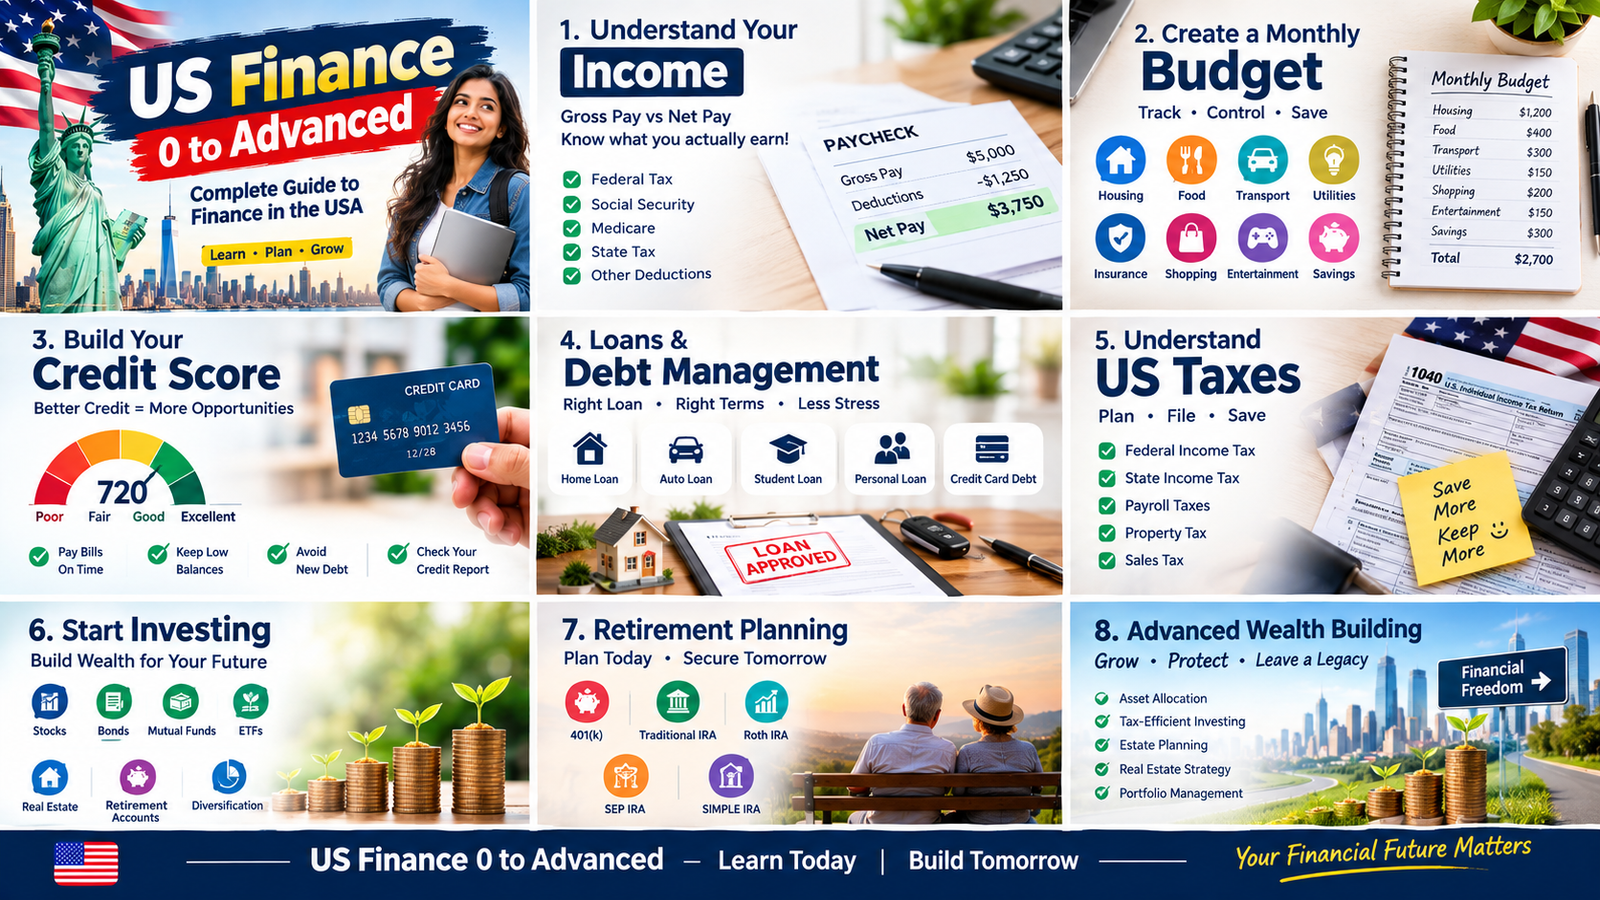
US Finance 0 to Advanced: Complete Guide to Finance in the USA
Understanding finance is one of the most important skills for anyone living, working, or doing business in the United States. From opening your first bank account and managing a paycheck to building credit, investing, paying taxes, planning retirement, and creating long-term wealth, financial knowledge can make a major difference in your future.
This US Finance 0 to Advanced guide explains the basics of the American financial system and gradually moves toward advanced topics. Whether you are a complete beginner or already understand personal finance, this guide can help you build a stronger financial foundation.
What Is US Finance?
US finance refers to the financial system of the United States, including banking, credit, investments, taxation, insurance, loans, retirement accounts, financial markets, and personal money management.
The US financial system includes banks, credit unions, investment companies, insurance providers, government agencies, financial markets, and millions of individual consumers.
For beginners, the easiest way to understand finance is to divide it into several major areas:
-
Banking
-
Income and budgeting
-
Credit and credit scores
-
Loans and debt
-
Taxes
-
Investing
-
Insurance
-
Retirement planning
-
Wealth management
Step 1: Understanding Your Income
The first step in personal finance is understanding how much money you earn.
In the United States, employees generally receive a gross salary or hourly wage. Your actual take-home pay is usually lower because taxes and other deductions may be taken from your paycheck.
Common paycheck deductions can include federal income tax, Social Security, Medicare, state income tax where applicable, and employer-related benefits.
Understanding the difference between gross income and net income is important because your monthly budget should generally be based on the money you actually receive.
Step 2: Create a Monthly Budget
Budgeting is the foundation of good financial management.
A simple budget divides your income into different categories such as:
-
Housing
-
Food
-
Transportation
-
Utilities
-
Insurance
-
Debt payments
-
Shopping
-
Entertainment
-
Savings
-
Investments
You do not necessarily need a complicated system. The goal is to know where your money is going every month.
Finance apps and budgeting tools can make this process easier by helping you track transactions and categorize expenses.
Step 3: Build an Emergency Fund
Before focusing heavily on investments, many people should consider creating an emergency fund.
An emergency fund is money kept aside for unexpected expenses such as a major repair, temporary loss of income, or other financial emergencies.
The appropriate amount depends on your income, expenses, job stability, and personal circumstances. A common approach is to gradually build several months of essential living expenses.
Keep emergency money somewhere relatively accessible rather than putting all of it into investments that may fluctuate in value.
Step 4: Understanding Credit in the USA
Credit is a major part of the US financial system.
Your credit history can influence your ability to qualify for loans, credit cards, mortgages, and sometimes other financial services.
A credit score is a numerical representation derived from information in your credit report. Different scoring models exist, but payment history, amounts owed, length of credit history, new credit, and types of credit can all be relevant.
To build healthy credit, focus on paying bills on time, managing balances responsibly, and avoiding unnecessary debt.
Step 5: Credit Cards
Credit cards can be useful financial tools when managed responsibly.
A credit card allows you to borrow money up to a specified limit and repay it later. Some cards offer rewards, cashback, travel benefits, or other features.
However, carrying a balance can result in interest charges. Credit card interest rates can be high, so paying the statement balance in full when possible can help avoid unnecessary interest.
Never treat a credit card limit as additional income.
Step 6: Loans and Debt Management
Loans are another major part of US finance.
Common types include:
-
Personal loans
-
Auto loans
-
Student loans
-
Mortgages
-
Business loans
-
Credit card debt
Before accepting a loan, look beyond the monthly payment. Consider the interest rate, loan term, fees, total repayment amount, and other conditions.
A lower monthly payment does not always mean a cheaper loan because extending the repayment period can increase the total interest paid.
Step 7: Understanding US Taxes
Taxes are an essential part of US personal finance.
Depending on your circumstances, you may encounter federal income taxes, state income taxes, payroll taxes, property taxes, sales taxes, and other taxes.
Tax rules can vary significantly depending on income, state, filing status, deductions, credits, investments, and other factors.
For complicated situations, professional tax advice can be valuable. Tax laws also change, so important tax decisions should be based on current official information.
Step 8: Start Investing
Once your basic financial foundation is established, investing can become an important part of long-term financial planning.
Common investment categories include:
-
Stocks
-
Bonds
-
Mutual funds
-
Exchange-traded funds (ETFs)
-
Real estate
-
Treasury securities
-
Retirement investments
Stocks represent ownership in companies. Bonds generally represent debt issued by governments or organizations. Funds can provide exposure to a collection of investments.
Every investment carries some level of risk. Higher potential returns generally come with higher uncertainty.
Step 9: Understand Diversification
Diversification means spreading investments across different assets rather than putting all your money into one investment.
For example, instead of investing everything in one company, an investor might use diversified funds containing many companies.
Diversification cannot eliminate investment losses, but it can reduce the impact of a poor performance from a single investment.
Your investment strategy should consider your goals, time horizon, risk tolerance, and financial situation.
Step 10: Retirement Planning
Retirement planning is one of the most important advanced areas of US personal finance.
Common retirement accounts include:
-
401(k)
-
Traditional IRA
-
Roth IRA
-
SEP IRA
-
SIMPLE IRA
Employer-sponsored retirement plans such as a 401(k) may provide opportunities for employees to contribute money toward retirement. Some employers also provide matching contributions under their plan rules.
Traditional and Roth accounts have different tax treatment, so understanding the differences is important before choosing an account or strategy.
Step 11: Advanced Wealth Building
Advanced personal finance goes beyond simply saving money.
It can involve:
-
Asset allocation
-
Tax-efficient investing
-
Retirement income planning
-
Estate planning
-
Insurance planning
-
Real estate strategy
-
Business ownership
-
Portfolio management
At this stage, financial decisions become more personalized. The right strategy for one person may not be appropriate for another.
Investors with substantial assets or complex financial situations may benefit from working with qualified financial, tax, and legal professionals.
Step 12: Protect Your Wealth
Building wealth is only one side of financial planning. Protecting it is equally important.
Insurance can help manage financial risks associated with health, property, vehicles, disability, and other unexpected events.
Estate planning can also become important as your assets and responsibilities grow. Depending on your circumstances, this may involve wills, beneficiaries, trusts, powers of attorney, and other legal documents.
US Finance: From Beginner to Advanced
The easiest way to learn US finance is to progress step by step.
Start with income and budgeting. Then learn about banking and credit. After that, understand loans and taxes. Once your financial foundation is stronger, learn about investing and retirement accounts.
Finally, move into advanced subjects such as portfolio management, tax planning, estate planning, and wealth preservation.
You do not need to understand everything at once. Financial knowledge develops over time through consistent learning and practical experience.
Final Thoughts
US Finance 0 to Advanced is a broad subject covering everything from managing your first paycheck to building long-term wealth.
The most important principle is to create a strong foundation before focusing on advanced strategies. Track your income, control expenses, build emergency savings, understand credit, manage debt carefully, learn how taxes work, and invest according to your goals and risk tolerance.
Financial markets and tax rules can change, so always verify important information using current official sources and consider professional advice for significant financial decisions.
The goal of learning finance is not simply to make more money. It is to understand how money works, make informed decisions, reduce avoidable financial mistakes, and build a more secure financial future.